UAE TO INDIA
Dubai to India Company Registration: UAE Parent Documents
Eight steps from Dubai to a running Indian subsidiary: MOFA attestation, costs in AED and INR, capital remittance and the compliance calendar.
Country Guides
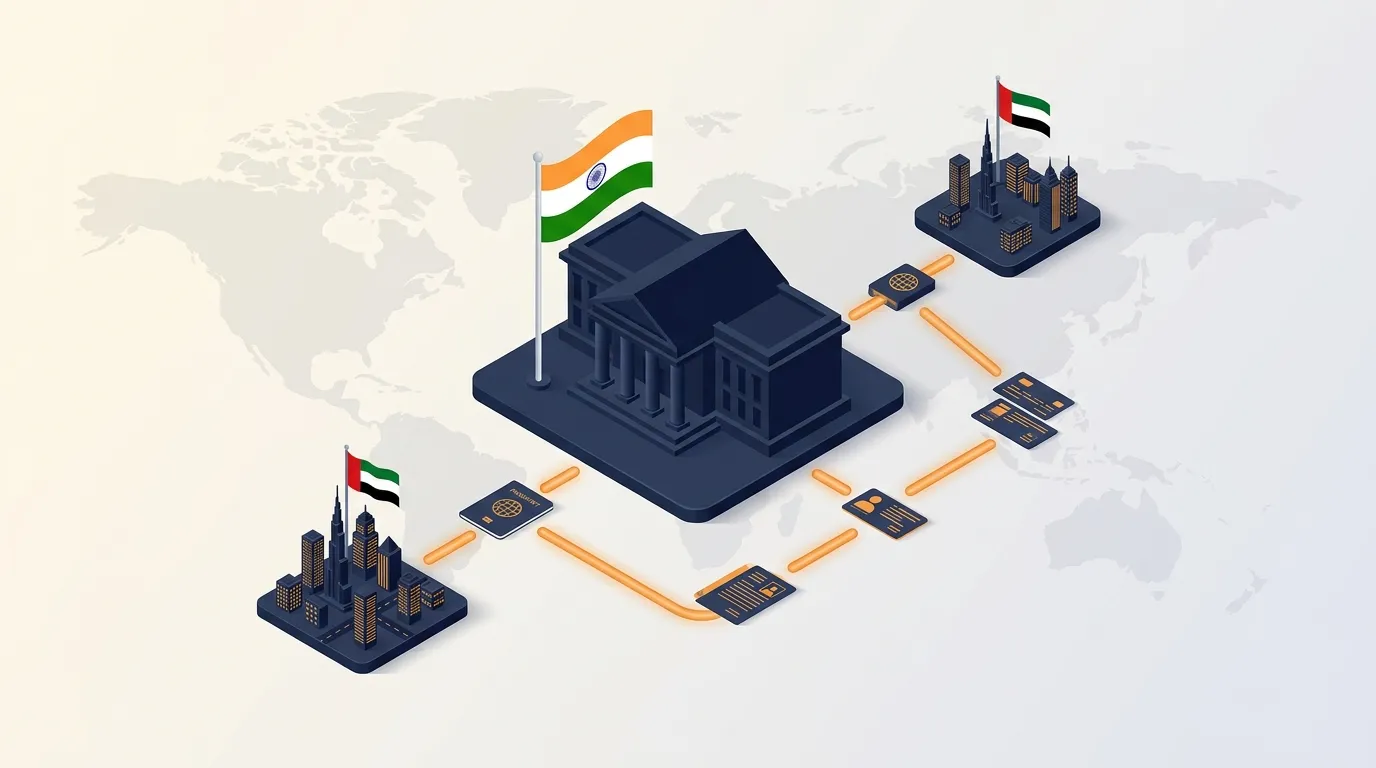
This guide is for a Dubai company that wants to own an Indian subsidiary, whether it is a free zone entity in DIFC, DMCC or JAFZA or a mainland LLC. Free zone parents should have a current trade licence and shareholder register ready, because Indian banks and the Registrar of Companies may ask about substance and beneficial ownership. The UAE is not a party to the Apostille Convention. Every parent document needs notarisation, MOFA attestation and Indian Embassy or Consulate attestation before India accepts it.
Setting up an Indian subsidiary from Dubai or Abu Dhabi is a well travelled path today, but the mechanics differ meaningfully from a typical foreign investor setup because of how the United Arab Emirates handles document attestation, banking, and the tax treaty position. This guide walks through the corridor specifically, not a generic "foreign company registering in India" checklist.
Here is how to register a company in India from Dubai, in eight steps:
- Choose the structure, almost always a wholly owned Private Limited subsidiary of the UAE parent
- Start the document chain early: notarisation, UAE MOFA attestation and Indian Embassy or Consulate attestation
- Obtain Digital Signature Certificates and director identification numbers for the directors
- Reserve the company name through SPICe+ Part A
- File SPICe+ Part B with the MoA, AoA and linked forms
- Receive the Certificate of Incorporation with PAN and TAN
- Open the Indian bank account and remit the share capital from the UAE
- Allot shares and file FC-GPR with the RBI within 30 days
Everything below unpacks the stages. Sibling corridor guides cover Singapore parents and US companies.
Why UAE companies are building in India now
India has become a natural next market for UAE based founders, particularly those running trading, logistics, technology, or professional services businesses out of Dubai, Abu Dhabi, or one of the free zones. The two economies sit close geographically, share large trade volumes, and increasingly share people, since a substantial number of Indian passport holders and NRIs (non resident Indians) run or co found UAE businesses.
The corridor in numbers
The corridor is large enough that direction matters more than precision: DPIIT data has consistently placed the UAE among India's top ten FDI sources, with equity inflows in the region of USD 3 billion in recent years, and bilateral trade above USD 80 billion makes the UAE one of India's largest trading partners. The CEPA trade agreement, in force since 2022, has pushed both numbers upward.
What usually triggers the move
In our experience advising UAE based founders, the decision to incorporate in India is usually triggered by one of a few things: an Indian client or distributor that will only contract with a locally incorporated entity, a hiring need that free zone structures cannot satisfy because of India specific labour and payroll requirements, or a founder who is an NRI and wants a compliant, on the books route back into the Indian market rather than an informal arrangement.
Choosing the structure from the UAE
Wholly owned subsidiary as the default
For most UAE parent companies, a wholly owned Indian subsidiary, incorporated as a Private Limited Company under the Companies Act, is the structure that makes sense. It gives the UAE entity full ownership and control, lets the Indian company contract, hire, invoice, and hold assets in its own name, and is generally the structure Indian banks, clients, and government departments are most comfortable dealing with. The foreign subsidiary service page covers how the structure is set up and maintained.
Branch and liaison office compared
A branch office or liaison office is occasionally proposed as a lighter alternative, but these routes need an application through an AD Category-I bank, which approves it. Prior RBI or Government approval applies only in specified cases. They come with restrictions on the activities the office can undertake in India, and are not designed for companies that intend to trade, manufacture, or build a full operating business in India. A liaison office in particular is meant only for representative activities and cannot generate local revenue. For a UAE company planning to actually operate in India, these are usually the wrong starting point.
Personal shareholding versus corporate parent
Some UAE resident founders, especially NRIs, ask whether they should hold shares personally rather than through their UAE company. Both are workable under current rules, but the choice affects how dividends and capital are taxed on the way back to the UAE, how the DTAA (Double Taxation Avoidance Agreement) between India and the UAE applies, and how future fundraising or exit will be structured. This is a decision worth taking to a chartered accountant before incorporation, not after, since restructuring shareholding later adds cost and paperwork.
How to register a company in India from Dubai: step by step process
SPICe Plus with a foreign parent
Indian company incorporation runs through an integrated online form generally referred to as SPICe Plus, which bundles company incorporation, PAN and TAN allotment, and a few other registrations into a single filing with the Registrar of Companies. When the shareholder is a foreign company rather than an individual, the process needs additional supporting documents from the UAE parent, and the review can take somewhat longer than a purely domestic incorporation, so it is worth planning for that.
Documents and legalisation
The UAE parent will typically need to provide a certified copy of its trade license or certificate of incorporation, its memorandum and articles or equivalent constitutional documents, a board resolution authorising the Indian subsidiary and naming an authorised signatory, and identity documents for the ultimate beneficial owners and proposed directors. Every one of these documents needs to go through a legalisation chain before Indian authorities will accept it, which is where the UAE corridor differs from, say, a US or UK parent.
DIN for foreign directors
Any individual who will be a director of the Indian company, including a UAE resident director, needs a Director Identification Number, obtained as part of the incorporation filing. This requires identity and address proof that has also gone through the same legalisation route, and photographs and signatures that meet Indian filing standards, so it is sensible to gather these early rather than midway through the SPICe Plus filing.
Resident director and registered office
At least one director must have stayed in India for at least 182 days during the financial year. For a newly incorporated company, the requirement applies proportionately at the end of its first financial year. Nationality does not replace this residence test. A resident director has statutory duties even when the overseas parent retains ownership. See section 149 of the Companies Act.
Documents and MOFA attestation required from Dubai
- Trade licence or certificate of incorporation of the UAE parent, free zone or mainland
- Memorandum and articles or equivalent constitutional documents
- Board resolution authorising the Indian subsidiary and naming the authorised signatory
- Shareholder register and beneficial ownership details of the UAE parent
- Passport and proof of address of each proposed director and beneficial owner
- Photographs and specimen signatures for the DIN and DSC applications
Each document needs notarisation and MOFA attestation in the UAE, then attestation by the Indian Embassy or Consulate, before Indian authorities accept it. The UAE is not a party to the Apostille Convention. How long the chain takes depends on your documents and the UAE authorities, so start it before anything else; it is the critical path of the whole timeline.
Dubai and UAE specifics that change the playbook
Freezone versus mainland parent
Whether the UAE parent is registered in a free zone such as DIFC, DMCC, JAFZA, or one of the others, or is a mainland LLC, changes some of the paperwork Indian authorities will expect. Free zone entities sometimes hold a different kind of license and reporting structure than mainland companies, and Indian bankers and the Registrar of Companies may ask more questions about the free zone entity's actual trade license, its beneficial ownership register, and whether it has full operating substance rather than being a pure holding shell. None of this is disqualifying, under current practice, but it does mean free zone parents should expect a slightly closer look and should have their trade license and shareholder register documents ready and current.
MOFA attestation instead of apostille
This is the detail that trips up most UAE founders coming from a US or European background. The UAE is not a party to the Apostille Convention, so UAE documents cannot be apostilled for India. Each UAE issued document needs notarisation, then attestation by the UAE Ministry of Foreign Affairs (MOFA), then attestation by the Indian Embassy or Consulate in the UAE. Indian authorities accept the document only after all three steps. This chain takes real calendar time and should be started as early as possible, ideally in parallel with drafting the incorporation documents rather than after.
Tax treaty and CEPA angle
India and the UAE have a Double Taxation Avoidance Agreement that governs how dividends, interest, royalties, and certain other cross border payments are taxed between the two jurisdictions, and the Comprehensive Economic Partnership Agreement (CEPA) between the two countries has also lowered friction for trade in goods and services across the corridor. The specific rates, thresholds, and beneficial ownership tests under the DTAA are the kind of numbers that genuinely change with amendments and protocols, so any founder relying on a specific withholding rate or treaty benefit should have it verified against the current treaty text by their chartered accountant rather than relying on older summaries found online. As a planning anchor, the treaty has generally capped dividend withholding at 10 percent, and the full route for moving profit out is in repatriation of profits from India.
Money in, money out
Capital remittance and FC-GPR
The deadlines and portal mechanics are covered in the FC-GPR filing guide, and you can sanity check your own dates on the FC-GPR deadline calculator.
When the UAE parent remits share capital into the Indian subsidiary's bank account, the Indian company is generally required to report the inward foreign investment to the Reserve Bank of India through a filing usually referred to as the FC-GPR, within a defined window after share allotment, under current FEMA (Foreign Exchange Management Act) rules. Getting this filing right, and on time, matters more than most first time founders expect, since delays or errors here can complicate later fundraising, RBI compounding applications, or bank due diligence.
Separately, once the Indian subsidiary starts making payments back to the UAE parent, whether that is a management fee, royalty, dividend, or interest on a loan, some of these payments attract withholding tax and require certification filings under the Income-tax Act, 2025. For remittances from 1 April 2026, these are Forms 145 and 146 under the Income-tax Rules 2026 (formerly Forms 15CA and 15CB under section 195 of the 1961 Act). The applicable forms, provisions, and rates should be confirmed with your chartered accountant at the time each remittance is actually made, particularly given the transition to the new Income Tax Act, since form numbers, section references, and procedural requirements are the kind of detail that should never be taken from an older article rather than checked against current guidance.
Banking friction when remitting AED
UAE banks and Indian banks both run their own compliance checks on cross border capital movement, and UAE founders often find that the Indian bank asks for more supporting paperwork than expected, including KYC documents for the UAE parent, the board resolution authorising the investment, and sometimes a declaration on the source of funds. The FC-GPR comes later, within 30 days of share allotment. Building in a buffer of a few extra days on either side of the actual transfer, and choosing a bank on the Indian side that already has some experience with UAE inbound remittances, tends to save real frustration.
NRI promoters returning via Gulf
A recurring pattern in this corridor is the NRI who built a business in Dubai or another emirate and now wants to invest back into India, either alongside Indian resident co founders or as the sole promoter. This is generally workable under current FEMA and company law, but the structuring needs care around residency status, the source of the investment, and whether the individual is investing personally or is routing the investment through their UAE company, since each route carries a different compliance and tax trail.
Compliance calendar after day one
FC-GPR, FLA and FEMA rhythm
Beyond the initial FC-GPR filing at the time of capital infusion, the Indian subsidiary of a UAE parent generally needs to file an annual Foreign Liabilities and Assets (FLA) return with the Reserve Bank of India, reporting the outstanding foreign investment and any foreign liabilities as of the end of the financial year. This is separate from, and in addition to, the company's regular tax and ROC (Registrar of Companies) filings, and missing it tends to surface later as an awkward compliance gap during due diligence or fundraising. The FLA return guide covers the annual cycle, FC-GPR vs FC-TRS covers the event based forms, and owning all of it is what a FEMA compliance retainer is for.
ROC GST and payroll basics
Once operating, the Indian subsidiary has the usual rhythm of Indian corporate compliance: annual financial statements and annual return filings with the ROC, income tax return filing, GST registration and periodic returns if the business is supplying taxable goods or services above the applicable threshold, and payroll compliance including provident fund and employee state insurance registrations once the company starts hiring staff in India. None of these are unique to a UAE parent, but they do need an India based team or retainer firm managing them on a fixed calendar, since Indian filing deadlines are generally strict about timing. GST specifics are on the GST registration service page, and recurring charges to the parent need a transfer pricing position from year one.
What a monthly retainer should cover
A sensible monthly or quarterly retainer for a UAE owned Indian subsidiary should cover bookkeeping and management accounts, GST return filing if applicable, TDS (tax deducted at source) compliance on salaries and vendor payments, payroll processing, and a periodic check in on FEMA filings like the FLA return, so that nothing falls through the gap between the incorporation team and the accounting team. It is worth asking any firm you engage exactly which of these are included versus billed separately, since "compliance" means different things to different providers.
Cost to register a company in India from Dubai (and the timeline)
A realistic all in budget
| Cost item | Typical range |
|---|---|
| Government charges (name, filing, stamp duty, PAN, TAN) | ₹3,000 to ₹15,000 (roughly AED 130 to AED 660) |
| Digital Signature Certificate, per director | ₹1,500 to ₹3,000 |
| Notarisation plus MOFA attestation, per document | AED 150 to AED 600 |
| Indian Embassy or Consulate attestation | AED 100 to AED 400 per document |
| Krystal7 Consultants' professional fee, cross border incorporation | USD 1,200 to 1,700 (about INR 1,15,000 to 1,63,000) |
| Krystal7 Consultants' compliance retainer, year one | From USD 300 a month (USD 3,600, about INR 3,45,000, a year) |
Setup costs for an Indian Private Limited Company from a UAE parent typically include government incorporation fees, professional fees for the incorporation itself, DIN and digital signature costs for each director, MOFA attestation and Indian Embassy attestation charges in the UAE, and the first year of registered office and compliance retainer fees. These figures move with government fee schedules and market rates, so treat the table above as planning ranges and ask your service provider for a current, itemised quote broken into government fees, professional fees, and legalisation costs, and treat any all in quote that does not separate these three as one to question.
Week by week timeline
| Stage | Typical time |
|---|---|
| Notarisation, MOFA and Indian Embassy attestation in the UAE | Depends on your documents and the UAE authorities |
| DSC, DIN, name reservation and document drafting | 2 to 3 working days for the name, then 2 working days to draft |
| SPICe+ filing and MCA processing | 2 working days to file, then 2 to 3 working days to the Certificate of Incorporation |
| Bank account, capital remittance and share allotment | 2 to 3 weeks |
| FC-GPR filing | Within 30 days of allotment |
About four to five weeks to a bank account and GST is realistic from Dubai, plus attestation time. FC-GPR follows within 30 days of allotment. The attestation chain is the dominant variable. The wider decision set is in the Expanding to India guide.
A realistic timeline, assuming documents are gathered promptly, generally runs through a few distinct phases: preparing and legalising the UAE parent's documents through the MOFA and embassy chain, which is usually the longest single step and depends heavily on how quickly the UAE side moves; obtaining DIN and digital signatures for directors; filing SPICe Plus and waiting for Registrar of Companies approval; and then opening the Indian bank account and completing the FC-GPR filing once capital arrives. Marketing pages that promise incorporation in a handful of days are usually describing only the Registrar of Companies step and quietly excluding the legalisation chain, which is often the slowest part of the whole process for a UAE founder.
For the structure most foreign parents choose, read the wholly owned subsidiary in India guide, or go straight to the foreign subsidiary registration service for the fixed fee scope.
Frequently Asked Questions
Can a United Arab Emirates company own 100 percent of an Indian subsidiary?
Under current FDI (foreign direct investment) rules, most sectors allow 100 percent foreign ownership through the automatic route, meaning a UAE parent can generally hold the entire share capital of its Indian subsidiary without needing prior government approval. A small number of sectors carry sector specific caps or conditions, or fall under the government approval route instead of automatic approval, so it is worth confirming the sector classification for your specific business with a chartered accountant before assuming full ownership is available.
How long does it take to register an Indian company from United Arab Emirates?
A realistic timeline, including document legalisation through the MOFA and Indian Embassy chain in the UAE, generally runs to several weeks rather than the handful of days sometimes advertised, since the legalisation step alone can take meaningful time and is largely outside the control of the Indian side of the process. Founders who start gathering and legalising documents in parallel with planning the incorporation tend to move noticeably faster than those who wait until the filing is ready to begin the attestation chain.
Do I need to travel to India to incorporate?
No, the entire incorporation process, including obtaining director identification numbers, digital signatures, and filing SPICe Plus, can generally be completed remotely from the UAE, with documents signed, notarised, and legalised locally before being couriered or uploaded as required. Many UAE founders never visit India during the incorporation itself, though a visit is often useful once operations begin, particularly for opening the Indian bank account in person if the bank requests it.
What does it cost to set up and run an Indian subsidiary?
Setup costs cover government incorporation fees, professional fees, DIN and digital signature charges, and UAE side legalisation costs, while ongoing annual costs cover statutory audit, ROC filings, income tax return filing, and any GST or payroll compliance once the business starts operating. These figures vary by service provider and by how much activity the company actually has, so ask for a current itemised quote from your incorporation firm rather than relying on a generic number, since this is precisely the kind of figure that changes with government fee revisions.
Should an NRI in Dubai invest as an individual or through a UAE company?
Both routes work under the automatic route, but they differ on repatriation tax and exit mechanics: an individual NRI shareholding keeps entry simple, while a UAE corporate parent can use the India UAE treaty position on dividends. The right answer depends on PAN status, the remittance source account and where profits should land, which is exactly what we map before incorporation.
Can an NRI register a company in India?
Yes, an NRI can generally register a company in India, either as a shareholder in their personal capacity or through a foreign entity such as a UAE company they own, and can also serve as a director subject to the usual resident director requirement being met by at least one other board member. The exact structuring, particularly around funding the investment and repatriating returns, is worth discussing with a chartered accountant given the specific FEMA and tax considerations that apply to NRI investment.
How much will it cost to register a company in India?
The core government incorporation fee for a Private Limited Company is generally modest and tied to the company's authorised capital, but the realistic all in cost also includes professional fees, digital signature and DIN charges, stamp duty which varies by state, and for a foreign parent, the additional legalisation costs on the UAE side. Because government fee schedules and state stamp duty rates are revised periodically, it is best to confirm current figures with your incorporation provider rather than rely on older published numbers.
Which guide should a Dubai-based company use for the full India setup?
Use the UAE to India registration guide for the complete journey. This Dubai guide adds the parent-document, signing and funding questions to prepare before the incorporation engagement.
NEXT STEP
Put this step into your India entry plan
Continue with the UAE guide for the full registration journey, from ownership and documents to banking and ongoing compliance.
WRITTEN BY
Nihal Srivastava
Co-FounderNihal Srivastava is a co-founder of Krystal7. He leads client delivery and operations, working with foreign founders on India entry, business structuring and cross border compliance.
Filed under Country Guides · All corridors